

USAA Mobile analysis by Appwee
I look at finance apps differently from entertainment apps: a banking tool has to be dependable when I am tired, travelling, or trying to solve a problem quickly. USAA Mobile is built around that practical need, bringing USAA insurance, banking, and investment accounts into one mobile experience. After using it as an everyday financial hub, I found its biggest strength is not a flashy interface but the way it keeps several parts of a USAA relationship close together.
That focus also defines who should choose it. If I already use USAA for financial services, the app makes far more sense than maintaining separate tools for a bank, an insurer, and an investment provider. If I have no USAA relationship, however, installing it alone does not offer much value. This is a free finance app from USAA, rated for Everyone, and its usefulness depends heavily on whether its connected services match my situation.
How I judged USAA Mobile as a daily finance tool
My first test for an app like this is speed of orientation. When I open it, can I understand my financial position without digging through several unrelated screens? The second is workflow: can I move from checking an account to handling an insurance question without feeling that I have switched applications? The third is trust. Financial information needs a more restrained, predictable experience than a shopping or social app.
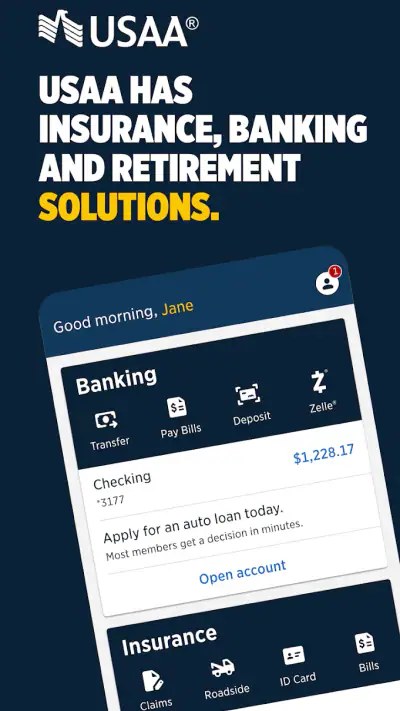
USAA Mobile performs best when I treat it as a central dashboard rather than as a specialist tool for only one task. The combination of banking, insurance, and investment access gives it a wider role than a simple checking-account application. That matters for someone who wants one place to review different parts of a household’s financial life, especially when a car, home, cash account, and investments are all connected to the same provider.
The app has a 4.7 average from around 497 thousand ratings, and it has passed 10 million installs. Those figures do not replace personal testing, but they do suggest that the mobile experience has become a regular part of many customers’ routines. I also appreciate that the developer is clearly identified as USAA rather than an unrelated companion service, which makes the app’s purpose immediately understandable.
The first decision: are you already in the USAA ecosystem?
This is the question I would answer before thinking about screens or convenience. For an existing USAA customer, the app can reduce the need to remember separate access points. I can imagine checking an account balance, reviewing an insurance matter, and looking at investments during the same short session without opening several provider apps.
For someone comparing banks, the situation is different. USAA Mobile is not a universal personal-finance organizer that becomes equally useful with accounts from every institution. Its appeal is tied to USAA services. A person who wants a neutral app to combine unrelated banks, cards, loans, and investments may be better served by a dedicated budgeting or aggregation product, depending on the features and institutions they need.
That distinction prevents a common mistake: judging the app only by its download price. It is free to install, but the real commitment is choosing USAA as part of a broader financial relationship. I would therefore evaluate the underlying banking, insurance, and investment services separately before switching. The app is a strong reason to value that relationship, not a substitute for evaluating it.
What feels most useful in everyday situations
One realistic scenario is a busy weekday morning after a car-related incident. I may need to check available money, confirm a recent transaction, and deal with an insurance task while commuting or waiting for assistance. Having banking and insurance access in the same app reduces the mental load of deciding which provider to open first. That is a small convenience, but in stressful moments small conveniences matter.
Another scenario is monthly household administration. Instead of waiting until I am at a computer, I can use a short phone session to review accounts, check whether a payment has cleared, and then look at an investment account. I would not make a major financial decision merely because a mobile screen is convenient, but the app makes routine awareness easier. That can be more valuable than a long list of decorative features.
A third use is travel preparation. Before leaving, I would want a quick way to review relevant accounts and know where to go if an insurance or banking issue appears. The advantage here is not that a phone replaces every support channel; it is that the app gives me a familiar starting point. I can begin with the account or service connected to the problem instead of searching through old messages or separate applications.
Where the combined approach wins
The clearest advantage is context in one place. Many finance apps are excellent at one job: a bank app handles deposits and payments, an insurer app focuses on policies and claims, and an investment app concentrates on portfolios. USAA Mobile brings those categories together for people whose services are with USAA. That makes it particularly attractive to customers who dislike fragmented financial administration.
I also value the reduced switching cost during ordinary tasks. Moving between services inside one branded environment feels more coherent than remembering different passwords, layouts, and support paths. Even when I only need one feature, knowing that the other parts of my relationship are nearby can make the app feel like a genuine financial home base rather than a single-purpose utility.
The breadth also helps with visibility. Banking, insurance, and investments are often treated as separate chores, even though they affect the same household budget. Seeing them through one provider’s mobile experience can encourage me to think about cash flow, protection, and long-term money together. The app does not magically provide financial planning, but it makes the boundaries between those areas less inconvenient.
Practical habits that make the app more useful
I would begin by organizing my own routine around short, purposeful visits rather than constantly checking balances. A quick review after a regular payday, a separate insurance check when something changes, and an occasional investment review are more sensible than opening a finance app repeatedly out of anxiety. The app’s value comes from making those visits easy, not from encouraging compulsive monitoring.
I would also use the app as the first stop for identifying which USAA service is involved in a problem. If a charge looks unfamiliar, I would start with banking. If the issue concerns a vehicle or property, I would look toward insurance. If the question involves long-term holdings, I would enter the investment area. This sounds obvious, but a single app can blur categories; deliberately choosing the right area helps prevent confusion.
A less obvious benefit is the ability to keep routine administration mobile. I do not need to reserve every small check for a desktop session. That is useful for people who manage finances between work, family, and travel. At the same time, I would avoid using the phone as the only place where I understand my finances. For detailed planning, a larger screen, written records, or a conversation with a qualified professional may still be better.
Where another type of app may fit better
A specialist bank app may be preferable if my only priority is everyday spending and I want an experience built entirely around one checking or savings relationship. A dedicated investment platform may be more suitable if portfolio analysis, research, or trading tools are my main concern. An insurance-focused app may offer a more concentrated workflow for someone who rarely uses banking or investments through the same provider.
There is also a case for a budgeting app. If my accounts are spread across several financial institutions, a neutral overview may be more useful than a provider-specific dashboard. I would choose that route when the main problem is categorizing spending across unrelated accounts rather than managing a single USAA relationship.
This does not make USAA Mobile weak; it makes its design choice clear. It prioritizes connected access over being a universal tool for every financial provider. I would skip it if I am looking for an independent money-management layer, if my main need is advanced investment analysis, or if I do not use USAA services. In those cases, another category may solve the actual problem more directly.
Security and convenience require a sensible balance
Finance apps always involve a trade-off between quick access and careful access. I like the convenience of a mobile dashboard, but I would still treat my phone as a sensitive device. I would keep the operating system current, use a strong device lock, and avoid reviewing private financial information on an unsecured public device. Those are habits I would apply to any banking app, but the combination of services here makes them especially important.
Convenience can also create overconfidence. A clean summary may make my finances feel simpler than they really are. I would verify unusual transactions, read important insurance details carefully, and avoid assuming that seeing an investment balance is the same as understanding its risk. The app can improve access; it cannot replace judgment.
Compatibility is another practical point. The current version is 11.15.2 and requires at least iOS or Android 12. That means I would check my phone before planning a switch, particularly if I keep an older device for financial access. A free app that cannot run on my phone is not a useful option, and upgrading a device solely for one application may not be worthwhile.
The real cost of changing providers
Switching to a new financial ecosystem involves more than downloading an app. I would need to consider direct deposits, recurring payments, insurance details, investment arrangements, saved account information, and the time required to learn a new support process. If I already use several USAA services, moving away could create more administrative work than expected because the relationship is interconnected.
On the other hand, if I am already unhappy with the underlying services, a convenient app should not keep me from comparing alternatives. Mobile access is important, but it should come after fees, coverage, account suitability, investment needs, and customer support. I would not move money or insurance simply because one dashboard feels easier to navigate.
For an existing customer, the switching cost may work in the opposite direction: staying with USAA Mobile can simplify daily administration because I do not have to rebuild a collection of separate apps. That is the strongest practical argument for it. The app rewards consolidation, while a fragmented financial life reduces its advantage.
Who will appreciate it most
I would recommend USAA Mobile to a USAA customer who wants a single mobile entry point for banking, insurance, and investments. It is especially suitable for people who value convenience during ordinary account checks, want fewer provider apps, and prefer handling routine financial administration from a phone.
It also makes sense for households where more than one financial category matters. Someone managing a vehicle policy, everyday money, and investments can benefit from the shared context. The app is less compelling for a person who only wants a budgeting tool, only needs sophisticated investing functions, or has accounts scattered across providers.
The age rating of Everyone makes it broadly accessible from a content perspective, but suitability still depends on the financial relationship behind the app. A young user, a busy parent, a frequent traveller, and a retiree may all use it differently. What unites the best-fit users is not age; it is a preference for keeping USAA-related tasks together.
My recommendation after weighing the trade-offs
My recommendation is straightforward: if USAA already handles important parts of your finances, I would install USAA Mobile and make it the first place I check for routine account and insurance tasks. Its combined structure is more meaningful than any single convenience feature, and the free price removes the barrier to trying the mobile workflow.
I would not recommend it as a reason to join USAA without comparing the actual services first. Nor would I choose it over a specialist investment or budgeting app when those are my primary needs. The best alternative depends on whether I want provider access, independent financial organization, or advanced tools in one narrow area.
In the end, I see USAA Mobile as a focused companion for a consolidated USAA relationship. It wins by reducing fragmentation, helps most in everyday moments when several financial questions overlap, and loses some appeal when my accounts or priorities sit outside that ecosystem. If that matches the way I manage money, the app is a practical mobile command center rather than just another banking shortcut.
Gallery
USAA Mobile Pros and Cons
- Quick access to balances
- transactions
- and account details
- Mobile check deposit is convenient for everyday banking
- Bill pay and transfers can be managed from one app
- Card controls help with reporting loss or suspicious activity
- Secure login options add protection for sensitive financial data
- Primarily useful for USAA members
- limiting its audience
- Some features may require additional verification or eligibility
- App performance can vary after major updates
- Advanced financial planning tools are relatively limited
- Certain service requests may still require contacting support
USAA Mobile Frequently Asked Questions
What is USAA Mobile, and who can use it?
USAA Mobile is the official banking and insurance app from USAA, designed to help eligible members manage their financial products from an Android or iOS device. You can typically use it to view accounts, transfer money, deposit checks, manage cards, review insurance information, and contact support. USAA membership eligibility generally applies to military members, veterans, eligible family members, and certain other qualified individuals, so verify your eligibility before downloading.
What can I do with the USAA Mobile app?
After signing in, the app provides access to many everyday banking and insurance tasks in one place. You can check balances and transactions, pay bills, transfer funds, deposit checks by taking photographs, manage debit or credit cards, locate ATMs, review policy details, request roadside assistance, and contact USAA. Available tools may vary depending on the products you have, your account permissions, and your location.
Is USAA Mobile safe for banking and insurance management?
USAA Mobile includes security features intended to protect account access and personal information, such as encrypted connections, secure login, device authentication, alerts, and options like biometric sign-in when supported by your phone. Nevertheless, no mobile service is completely risk-free. Download the app only from the official Google Play Store or Apple App Store, keep your operating system updated, avoid public Wi-Fi for sensitive actions, and never share verification codes.
Does USAA Mobile support mobile check deposits and money transfers?
Yes, eligible users can generally deposit checks through the app by photographing the front and back of a properly endorsed check and submitting it for review. The app also supports certain transfers between accounts and other payment features, although limits, processing times, eligibility rules, and availability can differ. Make sure the images are clear, retain the check until the deposit is confirmed, and follow USAA’s instructions for safe disposal.
Is USAA Mobile free to download, and what does it require?
USAA Mobile is generally free to download, although normal mobile data charges may apply depending on your carrier. You need a compatible Android or iOS device, an internet connection, and valid USAA login credentials to use account features. Some services may require additional verification or permissions, such as camera access for check deposits and notification access for security alerts. Always check the current store listing for supported operating-system versions.














